The licence is issued. The tenancy contract is signed, the visa file is moving, and your first customer is asking where to send the money. Then the bank replies with two lines: your application has not been approved. No explanation, and nobody to appeal to.
That email lands in a lot of inboxes. Opening a corporate bank account has quietly become the hardest part of setting up a business in the UAE, harder than the licence and harder than the visas, and most founders are unprepared for it because nothing else in the process behaves this way. Everywhere else, you pay the fee, you submit the papers, you get the thing. Banking does not work like that.
What is striking about most rejections is how avoidable they were. The overwhelming majority of rejected applicants are running honest businesses. They were not caught doing anything. They were simply unreadable to the person assessing the file, and unreadable is the one thing a compliance officer cannot sign off on.
That distinction changes what you do next. If you think you were rejected for looking suspicious, you will spend months protesting your innocence to people who never accused you of anything. If you understand you were rejected for being unclear, you fix the file and get banked.
What the bank is actually deciding
A compliance officer reading your file is not asking whether your company is legal. That question was settled at the licensing counter. The question in front of them is narrower and a lot colder: can I predict what will move through this account, and can I defend approving it in three years when someone audits this decision?
The second half explains almost everything else.
UAE banks do not clear dollars, euros or pounds on their own. They rely on correspondent banks abroad, and those correspondents periodically inspect who their UAE partners have taken on. One careless file will not sink a bank. A pattern of them can cost it a correspondent relationship, and losing correspondent access is close to fatal for any bank with international clients. So the risk appetite you run into in Dubai was partly written in New York.
This is also why that warm meeting with the relationship manager meant nothing. The RM sells. They do not decide. Your file goes to a risk and compliance team you will never meet, who never spoke to you, who read only what is on the page, and who carry personal accountability if the account later blows up. Saying no to an ambiguous file costs them nothing. Saying yes might cost them their job.
Once that sinks in, most rejection reasons stop looking random.
Your trade licence does much of the deciding before anyone reads the file
The activities printed on your licence are the first filter, and they get applied before a human being reads a word you wrote. Your activity codes are mapped against the bank's internal risk categories. Some pass without comment. Others drop your file into a queue where the default answer is already no.
The general trading trap
This one catches good businesses constantly, and it is entirely preventable.
A general trading licence feels like freedom. Buy and sell anything, no licence amendments later. To a bank it reads as the opposite. It says: this applicant cannot or will not tell us what they trade. If the bank does not know what you trade, it cannot build a transaction profile, and without a transaction profile it has no way of telling a normal month from a suspicious one once the money starts moving.
Compare two versions of the same client. One imports automotive spare parts from Guangzhou into Sharjah and sells to garages across the Northern Emirates. Known product, known corridor, predictable invoice sizes, predictable frequency. The bank can picture the statement before the account even opens.
The other is the same man with a general trading licence and a business plan promising to "trade in various goods." Identical business. Completely different outcome.
If what you do is narrow, licence it narrowly. Breadth on paper costs you nothing at the licensing stage and a great deal at the bank.
Sectors where most banks will not go
Some activities are perfectly legal but sit inside a very small circle of willing banks, and the file has to be close to flawless. Expect a hard road if your licence covers:
- Virtual assets and crypto, including brokerage, mining, custody and payments
- Precious metals and stones, particularly gold, diamond and bullion trading
- Money exchange, remittance and payment services
- Forex, CFD and other leveraged trading platforms
- Used vehicle trading and export
- Tobacco, weapons, adult content and anything gambling adjacent
- Multi-level marketing and network sales structures
- Charities and religious organisations moving donations across borders
If you sit in one of these, an application to the wrong bank burns an attempt you cannot easily get back, because the rejection follows your file. These sectors need a bank chosen deliberately for them, and a level of documentary evidence an ordinary trading company would never be asked to produce.
What your choice of free zone signals
Banks hold private opinions about free zones. They will never publish them, but the opinions exist, and they come from experience: which zones produce companies that turn out to be real, and which produce companies that go quiet after twelve months.
Zones that require physical premises and vet shareholders properly tend to smooth the path. Zones that sell a licence, a visa and a virtual address as a cheap bundle raise the exact question the bank is already worried about, which is whether anything happens at that address at all. DIFC and ADGM entities sit in a bracket of their own, because they arrive with a regulator the bank already trusts.
None of this makes a zone unbankable. It changes how much you have to prove.
The difference between a company that exists and a company that operates
Compliance teams are trained to spot one pattern above all others, and it helps to see it the way they do. The pattern is a company that exists on paper and nowhere else.
The signals are cumulative rather than individually fatal. A flexi-desk address shared with three hundred other companies. No tenancy contract. No staff, or one staff member who is also the owner and is rarely in the country. A Gmail address on the application form. No website, or a website assembled last month from stock photos with no company details on it. A phone number nobody answers. A projected turnover in the millions attached to a business with no visible means of producing it.
Every one of those has an innocent explanation. Stack them together and you have described, almost exactly, the profile the bank's own training material tells its staff to refuse.
Fixing it is not expensive. It does have to be real. A modest serviced office with a tenancy contract in the company's name. Email on your own domain instead of a free one. A website that agrees with your licence rather than contradicting it. A UAE number that a human being answers. Some evidence that the business does something: a signed supplier agreement, a purchase order, an invoice, a letter of intent from a customer who exists.
Banks are not asking you to be large. They are asking you to be visible.
Source of funds and source of wealth are two different questions
Most weak files fail here, and the failure usually begins with applicants not realising these are two separate questions.
Source of funds is about the account. Where does the money flowing through it come from, transaction by transaction? Receipts from named customers. Capital injected by shareholders. A loan from a named lender.
Source of wealth is about the person. How did the shareholder build their net worth across a working lifetime, long before this company existed? Twenty years of salary and bonuses. A business sold in 2019. A property disposed of. An inheritance.
Answer the first while ignoring the second and the file stalls, goes quiet, then dies. Answer either one in a single word and it dies faster. "Savings" is not an answer, and neither is "family money."
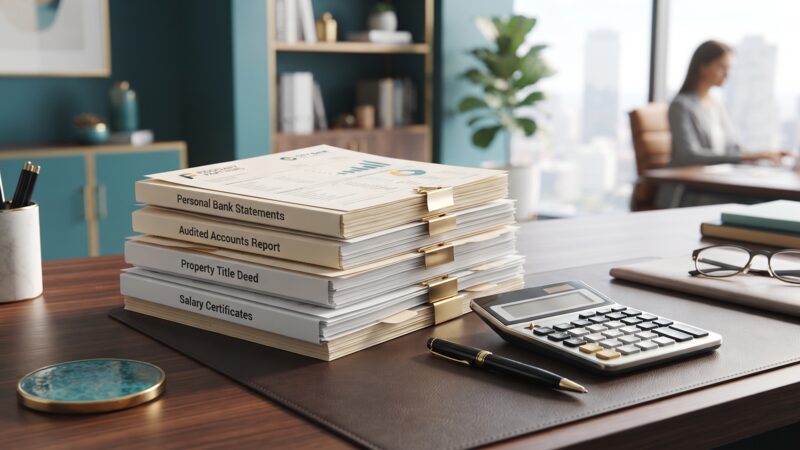
What satisfies a bank is a paper trail that runs in a straight line from where the money originated to the account you want to open. Personal bank statements from your home country covering six to twelve months. Audited accounts or tax filings from a previous company. A share sale agreement. A title deed and the contract that sold the property. Salary certificates. Probate documents.
None of it needs to be impressive. It needs to join up.
Prepare it before you apply, not when they ask. A file that answers the question on the first pass reads as competent. A file that produces documents grudgingly, one batch at a time, in response to escalating queries, reads as evasive. By the third round of questions, the officer has usually already made up their mind.
The people get screened harder than the company
Banks onboard people. The corporate structure is just the wrapper around them.
Every ultimate beneficial owner is screened, along with every authorised signatory and, frequently, every director. Names run against sanctions lists, politically exposed person databases and adverse media. Three things go wrong at this stage.
Jurisdiction is the first. Certain passports, and certain countries of residence, put a file into a category most banks decline as policy rather than judgement. It has nothing to do with you as an individual, and nobody at branch level has the authority to override it.
Political exposure is the second. If a shareholder, or a shareholder's spouse, parent or business partner, holds or recently held public office, the file needs senior approval and enhanced monitoring for as long as the account stays open. Many banks decline rather than carry that workload for a modest account. Nobody is accusing anyone of anything. It is simply a cost the bank would rather not absorb.
The third is the ugliest: the false positive. Screening databases match on names. If your name resembles somebody sanctioned, litigated against, or badly written about in the press anywhere in the world, the hit lands in your file and the burden of disproving it falls on you. Applicants who cannot quickly show they are a different person often watch their application expire without a word.
Then there is history, which follows shareholders around more than they expect. A previous rejection. An account closed by another bank. Bounced cheques. An unpaid facility or personal credit trouble. The credit bureau exposes some of it, and banks share a good deal more with each other than most applicants assume.
Your counterparties and trade routes can sink an honest business
This is the one that shocks people, because it takes profitable, well documented, entirely lawful trading companies and rejects them anyway.
The bank is not only assessing you. It is assessing who you transact with and where they sit. A business plan naming suppliers in one country and buyers in another is being read as a map, and that map gets checked against sanctions exposure and known evasion corridors.
Two situations do the most damage.
The first is trade with, or adjacent to, sanctioned jurisdictions, even where the goods and the payment are entirely legal under UAE law. The correspondent bank standing behind the dollar leg may take a stricter line than UAE rules do, and when those two views conflict, the UAE bank sides with its correspondent. Every time.
The second is dual-use goods: electronics, components, machinery and equipment with an obvious commercial purpose and a possible military one. If your product sits in that category and your buyers sit in a sensitive region, you are asking a bank to carry a risk it earns nothing for carrying.
You cannot argue your way out of this after submission. It has to be handled inside the business plan, with real clarity about what you sell, who buys it, what documentation travels with it, and what end-use controls you apply.
The rejections applicants cause themselves
A large share of declines have nothing to do with risk appetite. They are presentation failures, and they are the cheapest ones to avoid.
- Documents that contradict each other. The form states one turnover, the business plan states another, the website implies a different activity entirely, and the shareholder's name is spelled three ways across the passport, the licence and the memorandum. Compliance treats every inconsistency as a possible lie until somebody explains it.
- Fantasy projections. A first-year forecast in the tens of millions attached to two employees and no signed contracts tells the bank you are either exaggerating or concealing something. Both get declined.
- Applying to five banks at once. It feels efficient. It looks desperate, and banks can often see the pattern. Deliberate, sequential applications work far better than a scattergun.
- Sending the consultant to the compliance interview instead of the owner. The bank wants to hear the person who owns the business describe it in their own words. An owner who cannot explain their own suppliers, margins and customers is a serious problem, and no adviser can rescue that call from the next chair.
- Silence. Applications lapse constantly because a request for one more document landed in an inbox nobody checks. A stalled file eventually gets closed, and a closed file is a rejection wearing a politer name.
The commercial decline nobody calls a decline
Some rejections have nothing to do with your file at all, and the bank will never say so.
Onboarding a corporate client costs a bank real money in due diligence and in monitoring the account for as long as it stays open. If your expected balances and transaction volumes do not cover that cost, the account is not worth opening, however clean your paperwork is. That is what minimum balance requirements are really about, and they vary enormously between banks and between account tiers inside the same bank. An applicant who clearly cannot hold the required balance often receives a polite decline instead of an offer of something cheaper.
Segment mismatch works the same way. A two-person consultancy walking into a corporate desk built for large trading groups gets declined for being irrelevant to that desk, not for being risky.
This is why choosing the bank is a strategic decision rather than an administrative one. The same company, with the same documents and the same shareholders, can be declined by one institution and approved by another in the same month. Digital business banks such as Wio and Mashreq's NeoBiz, along with startup-focused products at banks like RAKBANK, have opened a workable route for small and newly formed companies that traditional corporate desks were never designed to serve. Products and criteria change often, so check the current terms before committing, but the principle holds. Apply where you fit.
What actually changes the outcome
Preventing a rejection is far easier than reversing one, so the order of operations matters more than the effort you pour in.
Choose the bank before you build the file, not after. Every institution has a profile it is comfortable with, and the file should be assembled to answer that bank's questions specifically. Narrow the licence to what you genuinely do. Build enough substance that the company is visibly operating. Write a business plan a stranger could read and use to predict your bank statement, with named suppliers, named customers, the product, the corridor, average invoice size, expected monthly volume and the currencies involved. Have the source of wealth pack ready before the first meeting rather than assembling it under pressure. Send the owner to the compliance call. Apply to one bank at a time, and do it properly.
If you have already been rejected, resist the urge to reapply straight away to the same bank. Most of them run a cooling-off period, and an unchanged file resubmitted only confirms their original decision. Find the real weakness, fix it, then approach a bank whose appetite actually matches your profile.
This is the stage where experienced help pays for itself, and it is what structured bank account assistance is for: matching your profile to the right institution and building a file that answers the questions before they are asked, instead of scrambling to respond once they have been.
The bottom line and where this is heading
Nobody should expect UAE banks to relax. The country's removal from the international grey list in 2024 did not soften onboarding, and it was never going to. The compliance machinery built during that period is permanent now, and correspondent banks abroad still set the ceiling on what UAE institutions can accept, whatever local regulators say.
What is changing is the shape of the door rather than its width. Digital business banks are making entry easier for small companies while demanding cleaner, more structured information from them. Corporate tax registration and audited accounts are working their way into onboarding conversations, which quietly rewards businesses that keep proper books and punishes those that do not. Substance requirements are getting firmer. Within a few years, the gap between a company built to be banked and a company built to be cheap will be obvious from the first document a bank opens.
Which is the whole point. Bankability belongs in the decisions you make before the company exists: which zone, which activities, which shareholders, which office, which story about where the money came from. Companies designed to be banked get banked. Companies designed to be cheap get rejected, then spend far more fixing it than they ever saved.
A rejection says less about your integrity than about your file. Files can be rebuilt.
Frequently Asked Questions
Almost never. UAE banks are not obliged to give a reason and generally will not, partly because explaining a compliance-based decline can amount to tipping off. You will usually receive a short notice with no detail. Identifying the real cause means reviewing the file against what that particular bank is known to care about.
Most banks apply an internal cooling-off period, commonly around six months, and resubmitting an unchanged file will simply be declined again. Reapplying only makes sense once the underlying issue has genuinely been resolved, whether that was the licence activity, the substance, the documentation, or a shareholder's profile.
Not always, but at least one resident signatory with an Emirates ID makes the file considerably easier, and many banks now insist on it. Companies where every shareholder lives abroad and nothing operates in the UAE face the hardest route, offshore structures most of all.
It is not prohibited but it works against you. It prevents the bank from building a predictable transaction profile, which is the thing they need most. If your real activity is specific, licence it specifically. The flexibility of a broad licence rarely repays the banking friction it creates.
A straightforward file usually takes a few weeks; a complex one takes considerably longer. Incomplete source of wealth documentation causes more delay than anything else, followed by contradictions between documents that trigger extra rounds of questions. Files that answer everything on the first submission move fastest.